Français
 Nederlands
The rise of digital loans
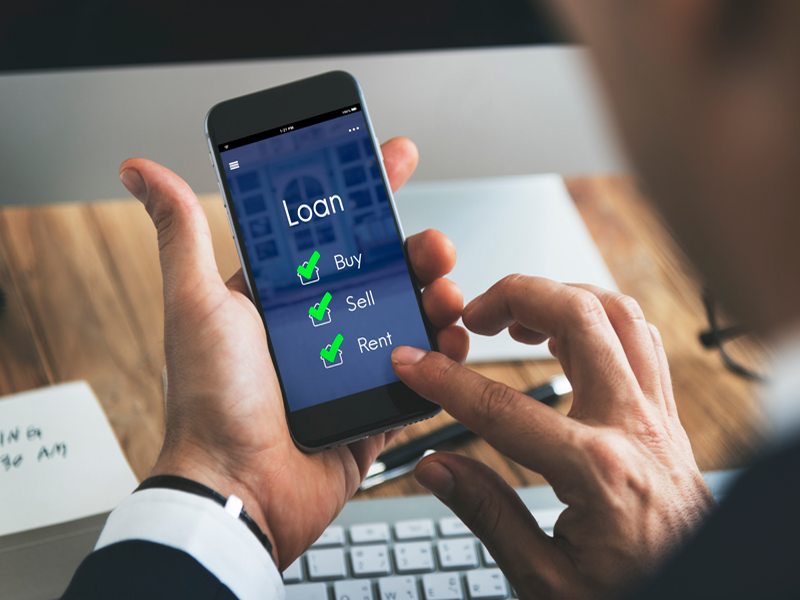
In the current digital age, applying for a loan is easier than ever before. With just a few clicks on a smartphone, consumers can gain instant access to liquidity, often without the involvement of a physical bank branch or extensive paperwork. This accessibility has fundamentally changed the financial market and offers opportunities for those looking to quickly bridge a shortfall. However, this speed is not without dangers. The ease with which one can borrow money often masks the true costs of the credit. Many consumers fail to realize that fast digital loans come with high interest rates and strict repayment terms that can jeopardize long-term personal financial stability.
Risks and financial pitfalls
The biggest challenge with digital loans lies in the impulsivity of borrowing behavior. Because the process is so streamlined, the reflection period often present in traditional loans is missing. This can lead to an accumulation of debt, where new loans are taken out to pay off old obligations. This process, also known as the debt trap, is a real risk for vulnerable groups seeking quick solutions for structural budget issues. Moreover, some online lenders operate in a legal gray area. Hidden costs and unclear terms make it difficult for the consumer to compare the effective cost price. It is therefore essential that users always read the fine print and look critically at annual percentage rates rather than being blinded by the attractive marketing promises often found in advertisements.
Responsible borrowing
To make responsible use of digital loans, education and awareness are required. Before agreeing to a digital loan, a thorough analysis of one's personal budget must be performed. It is crucial to determine whether the loan amount is necessary or if alternatives exist, such as building a buffer or adjusting spending patterns. Financial literacy is the most important line of defense against debt problems. In addition, it is advisable to only do business with recognized and regulated providers. An official lender is supervised by national financial authorities, providing some protection against malicious practices. By acting proactively and closely monitoring one's creditworthiness, one can leverage the benefits of modern technology without losing control over their own financial future. Maintaining an overview is the key to successful debt prevention in a digital economy.